A message from our CEO: What we learned travelling New Zealand with economist Cameron Bagrie.

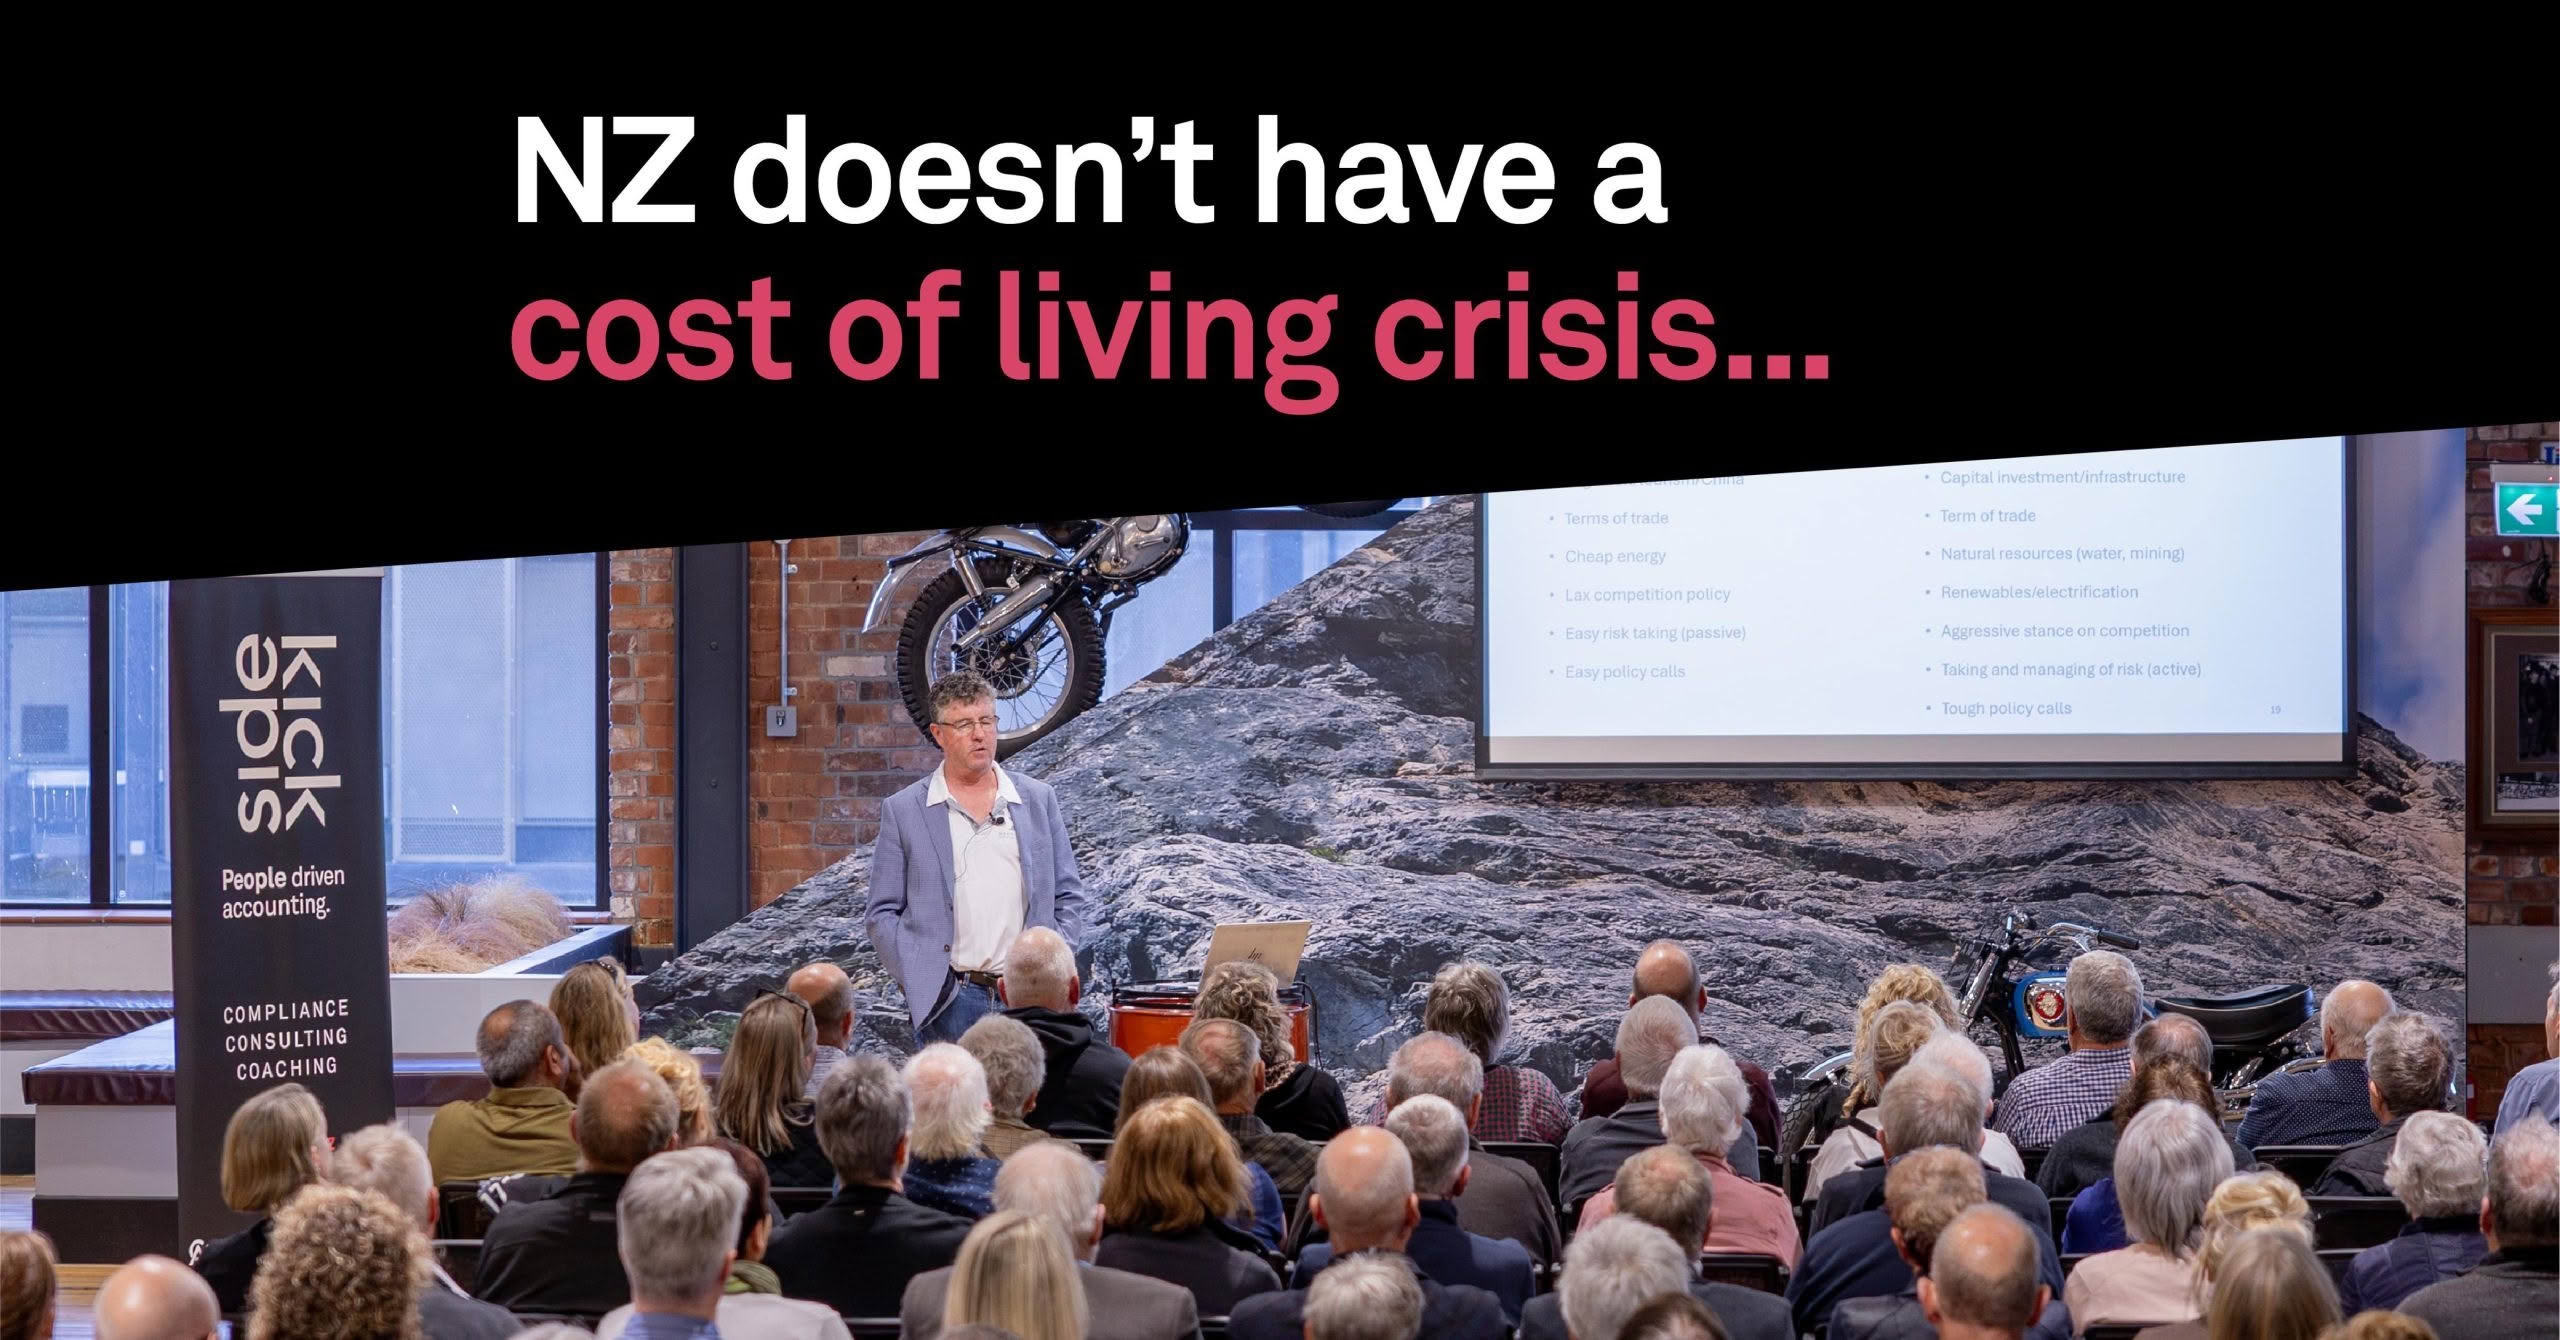
Over recent months, we’ve had the privilege of travelling around the country with independent economist Cameron Bagrie, bringing business owners, farmers, clients and our wider communities together for our Jandal-nomics roadshows.

We covered a lot of ground, from regional economic performance and productivity to banking, education and politics. While the conversations were different in each location, one message kept coming through:

New Zealand needs to get better at taking real risk for real reward.

There are reasons to be optimistic about where we’re heading, but also some big challenges we can’t keep avoiding.

Here are some of the key things we took away from the roadshow, and what they could mean for New Zealand businesses.

What does all this mean for your business?

New Zealand’s economic picture is more complicated than the headlines suggest. Some regions and industries are performing strongly, while others are still under pressure.

For business owners, the opportunity is to understand what’s happening around you, stay close to your numbers and be prepared to make decisions.

As Cameron put it throughout the tour:

“This is where the fun happens.”

Open the sections below to explore the conversations and ideas that stood out.

One country, several very different economies.

Cameron’s view was that the recovery is increasingly being driven from the South and moving upwards.

Canterbury, Otago and Southland are showing strength, with agriculture and other productive industries generating income, confidence and activity. This is more of an income-and-growth recovery than one built on borrowing and rising house prices.

The Wairarapa is showing similar resilience. Cameron described Wellington as an economy of two halves, with central Wellington continuing to face challenges while Greater Wellington and the surrounding rural economy are considerably stronger.

He had a particularly direct message about government:

“Local and National Government just getting to the ‘zero line’ – get out of the way! Just don’t **** it up!”

The point is that national economic headlines don’t always reflect what’s happening on the ground. A rural business could be having one of its strongest years while a nearby retailer, construction firm or professional services business is under pressure.

Business owners need to understand both the macro and the micro. What’s happening nationally matters, but so does the economy, industry and customer base immediately around you.

For around three decades, New Zealand operated through what Cameron called the “great moderation”: low inflation, cheap money, growing globalisation and rising house prices.

Cameron’s message was that this period is over.

We’re entering a world of greater volatility, geopolitical tension, demographic pressure, energy insecurity, inflation risk and changing trade relationships. Artificial intelligence will create enormous opportunities, but it will also disrupt established industries and jobs.

That might sound confronting, but Cameron wasn’t delivering a doom-and-gloom message.

As he said throughout the tour:

“This is where the fun happens.”

Volatility creates risk, but it also creates opportunity. Businesses that understand their numbers, make decisions quickly and stay disciplined can gain ground on competitors who are slower to respond.

The focus may need to shift from simply growing revenue to winning market share. The businesses that come out ahead may not be those with the biggest plans, but those that understand their customers and execute better.

Perhaps the most concerning statistic discussed during the tour was New Zealand’s productivity performance.

Depending on the period and measure used, labour productivity has increased by only around 0.3% to 0.4% a year over the past decade.

So what does productivity actually mean?

At its simplest, it’s about how efficiently we turn inputs into outputs. Labour productivity measures the real economic value produced for each hour worked.

It’s not about asking people to work longer or run faster. It’s about getting more value from the time, people, equipment and resources we already have.

That can come from better technology, improved systems, stronger management, investment in equipment, staff capability and removing unnecessary barriers.

The international comparison is sobering.

Labour productivity in the United States nonfarm business sector was 2.9% higher in the March 2026 quarter than a year earlier.

It’s not a perfectly like-for-like comparison, as the countries measure their productive sectors differently. But on Cameron’s 0.3% benchmark, the US achieved close to a decade of New Zealand’s recent productivity growth in a single year.

That’s a horrible statistic for New Zealand.

Productivity is what allows businesses to pay higher wages, invest in technology, compete internationally and generate the tax revenue needed to support public services.

Without productivity growth, increasing incomes becomes much harder. We either work more hours, add more people, take on more debt or accept lower living standards compared with other countries.

Agriculture is showing what productivity improvement can look like.

Using Stats NZ’s annual industry figures, labour productivity in agriculture increased by an average of approximately 2% a year between 2017 and 2025.

Annual results move around because farming is affected by weather, commodity prices and production cycles. But the underlying trend is encouraging.

Farmers continue to find ways to produce more value from their land, labour, equipment and technology.

They’re investing in genetics, technology, irrigation, systems, data and better on-farm practices, while adapting to changing regulations, environmental expectations, labour shortages and international markets.

Our farmers are doing an excellent job.

It also brings us back to Cameron’s challenge around the zero line:

Can we get out of productive businesses’ way and let them do what they’re good at?

If agriculture is achieving productivity gains of around 2% a year while New Zealand’s overall measured-sector average is only around 0.3% to 0.4%, it raises some serious questions about what’s happening elsewhere in the economy.

This isn’t about criticising individual workers. New Zealanders work hard. It’s about the systems around them: infrastructure, technology, management capability, access to capital and whether regulation makes it easier or harder to get things done.

We should be looking closely at the industries lifting productivity and asking what the rest of the economy can learn from them.

One of Cameron’s strongest challenges was that New Zealand needs to become more comfortable with taking real risk for real return.

He put it this way:

“We have more road-cones than sheep! We don’t know how to manage risk.”

That raises a difficult question about our banking system.

Banks often talk about backing business, but many business owners find that lending still needs to be supported by residential property. The bank may be lending to the company, but the security often comes back to the owner’s home and personal guarantee.

Reserve Bank data illustrates the wider shift. In June 2026, housing lending stood at approximately $400.5 billion, compared with $143.2 billion of business lending and $64.5 billion of agricultural lending.

Across those three categories, housing represents roughly 66% of lending, with business and agriculture making up the remaining 34%.

In mid-1998, the comparable split was approximately 53% housing and 47% business and agriculture. That’s a significant shift towards housing.

New Zealand won’t lift productivity simply by selling increasingly expensive houses to one another.

We need capital flowing into businesses, farms, technology, equipment, exports and people. These investments carry genuine commercial risk, but they’re also where sustainable productivity and higher incomes come from.

That doesn’t mean banks should lend recklessly. It means businesses, advisers, banks and policymakers need to find better ways to assess productive opportunities and share risk.

Cameron’s business, Chaperon, works in this space, helping businesses improve their bankability, understand their lending structures and negotiate more effectively with financiers.

Another important theme was education.

Cameron described school attendance as potentially one of our most important future economic indicators. It makes sense. Tomorrow’s workforce, productivity, innovation and social outcomes are all influenced by what’s happening in classrooms today.

Attendance improved nationally in early 2026, but regional differences remain significant.

Otago recorded the country’s highest regional attendance rate in Term 1 at 73%, with Canterbury and Southland close behind at 72%.

That’s encouraging for the South, but it shouldn’t create complacency. New Zealand’s overall attendance and educational performance still need considerable improvement.

Cameron had a particularly memorable way of describing the situation in some parts of the country:

“It’s about as cheerful as a coroner’s retirement speech.”

Education isn’t simply a government or school issue. It affects employers, families and communities. Businesses will eventually feel the consequences through workforce readiness, basic skills, resilience and the availability of capable people.

An economic strategy that ignores education isn’t really an economic strategy.

Cameron also raised the question of how we’re spending public money, comparing winter energy subsidies with investment in helping children achieve better educational outcomes.

When we began the roadshow, Cameron’s assessment was that the current National-led coalition appeared more likely than not to return to government.

I’m writing this during election week, and the political mood now looks considerably less certain.

The July Ipsos New Zealand Issues Monitor surveyed 1,002 adults and found Labour was perceived as the party most capable of managing all five of New Zealanders’ leading concerns: cost of living, healthcare, the economy, housing and unemployment.

Labour also overtook National on economic management, with 34% selecting Labour and 30% selecting National.

The Government received an average performance rating of 4.1 out of 10, with 24% giving it a positive score of seven or higher.

It’s important to be clear: the Ipsos Issues Monitor isn’t a party-vote poll, and it doesn’t tell us who will form the next government. But it does reveal a change in public perception.

That’s particularly interesting from our perspective. Many people in our immediate business network would traditionally lean towards National or ACT. It wouldn’t be unusual for perhaps 80% of a room of small business owners to sit somewhere around the centre-right.

Are those people genuinely moving left?

We’d be interested to hear what our clients think.

One July Taxpayers’ Union-Curia party-vote poll had Labour narrowly ahead of National, at 31.5% to 30.5%, but still projected the current National-ACT-New Zealand First coalition to retain a narrow parliamentary majority.

The same poll had approximately 38% of decided voters supporting parties other than Labour or National.

Our suspicion is that some disappointed National voters may not necessarily move directly to Labour. They may move sideways towards ACT, New Zealand First or the Opportunity Party, or simply become less engaged.

This election may be decided as much by movement between parties on the same side of the political spectrum as by voters crossing from right to left.

For business owners, the important thing is to understand the policy direction and potential changes that could affect your business, rather than relying on assumptions about what the next government might do.

Why Sidekick hosts these events

For Sidekick, these events are about much more than hearing an economic presentation.

Our mission is to help our clients be more successful, and bringing people together is an important part of that.

We’re a people-driven organisation. We want our clients to understand what’s happening beyond their own businesses, meet others facing similar challenges and leave with ideas they can put into action.

The roadshow conversations have reinforced just how important it is to look beyond the day-to-day, challenge the way we think and be prepared to make decisions.

We’ll continue sharing insights with our clients and communities, and we’re already looking forward to taking to the road again next year.

In the meantime, talk to your Sidekick advisor about what these economic, financial and regional changes could mean for your business.

Thank you, Cameron

A huge thank you to Cameron for his energy, openness, humour and outstanding effort throughout the tour.

Cameron has a rare ability to turn complicated economic information into practical, straight-talking insights that people can understand and act on.

You can follow his economic analysis through Bagrie Economics, which provides independent economic research, presentations and strategic advice.

Cameron is also involved with Chaperon, supporting businesses to become more bankable and navigate their financing relationships, and Equity Release NZ, which provides independent information about equity-release and reverse-mortgage options.

He also serves as the inaugural Chair and Spokesperson for The Parents’ Alliance, a non-partisan lobby group launched in September 2026 to advocate for parents within New Zealand’s education sector. As a prominent independent economist and father of two, Cameron’s involvement stems from a core belief that educational outcomes directly dictate New Zealand’s future economic prosperity

We’re in a fascinating, and occasionally uncomfortable, economic period.

The old playbook may no longer work. But for disciplined, informed and adaptable businesses, there is still plenty of opportunity ahead.

And one final thought that might make you smile: Cameron thinks Aussies are in for a shocking couple of years and New Zealand will gain a lot from that!

That’ll teach them for the underarm bowl.

Thanks for reading.
Ric Thorpe
Ric ThorpeCEO, Sidekick Holdings