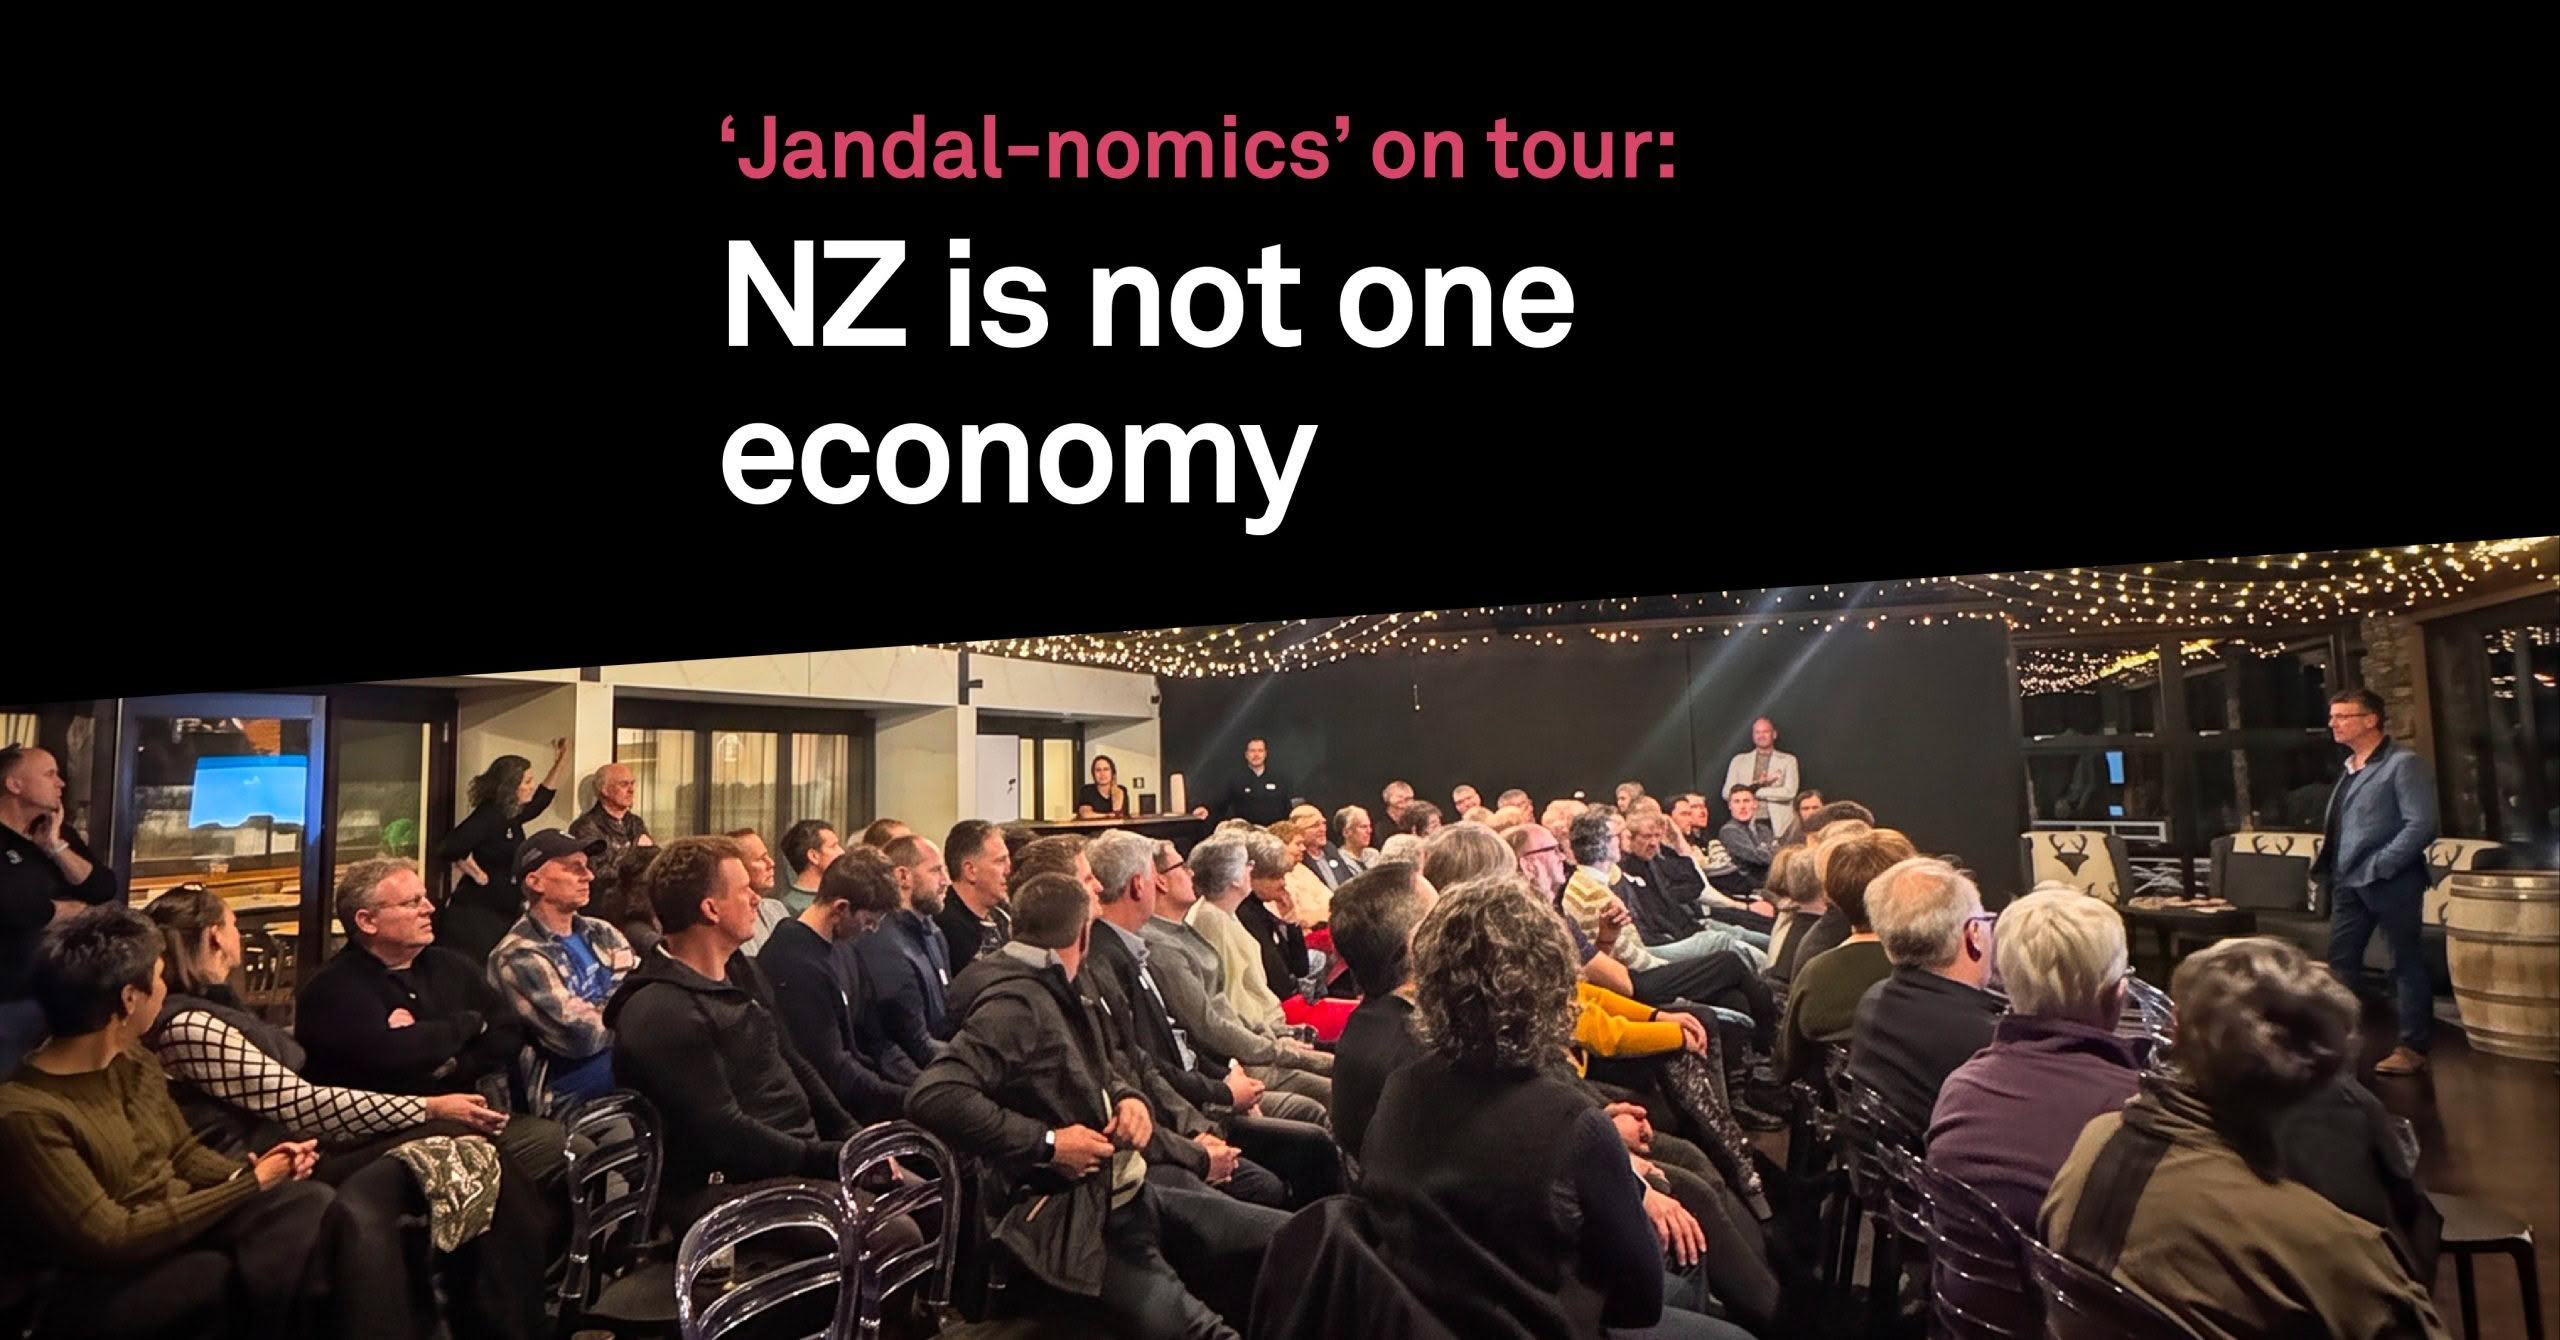
Jandal-nomics on tour: New Zealand is not one economy
A message from our CEO: What we learned travelling the country with Cameron Bagrie
In this article I’ll cover what we learned about business and NZ Inc, productivity, the rural performance, banking, education and politics. And there’s an underlying theme! Taking real risk for real reward!
Over recent months, Sidekick has had the privilege of travelling around the country with independent economist Cameron Bagrie.
Our Jandal-nomics events brought together business owners, farmers, clients and members of our wider communities in Otago, Canterbury and the Wairarapa. The economic themes were national and international, but the conversations in each room were distinctly local.
There is no single New Zealand economy.
Different regions, industries and communities are moving at very different speeds. There are genuine reasons for optimism, but also some major challenges that New Zealand cannot continue to avoid.
Geography: one country with several economies
Cameron’s view was that the recovery is increasingly being driven from the South and moving upwards.
Canterbury and Otago are showing strength. Agriculture and other productive industries are generating income, confidence and activity. This is not simply another recovery built on borrowing more money and spending it through the housing market. It has more of the characteristics of an income-and-growth recovery.
The Wairarapa told a similarly interesting story.
Cameron described Wellington as an economy of two halves. Central Wellington continues to face significant issues, while Greater Wellington and the surrounding rural economy are considerably stronger. The Wairarapa is benefiting from productive industries and a comparatively resilient rural sector, even while the central city is dealing with falling activity and the effects of public-sector meddling. Cameron spoke about “Local and National Government just getting to the ‘zero line’ – get out of the way! Just don’t **** it up!”
Where these differences matter, a national headline can say the economy is weak while a rural business is having one of its strongest years. Equally, a strong export return does not automatically flow through to every retailer, construction firm or professional service business in the nearest city.
Business owners need to understand both the national picture and the economy immediately around them. Looking at both macro and micro.
Economy: throw out the old playbook
For three decades, New Zealand operated through what Cameron called the “great moderation”:
Low inflation, cheap money, growing globalisation, rising house prices and a general expectation that the economic system would continue moving forward.
Cameron’s message was that this period is over.
We are entering a world of greater volatility, geopolitical tension, demographic pressure, energy insecurity, inflation risk and changing trade relationships. Artificial intelligence will create enormous opportunities, but it will also disrupt established industries and jobs.
That may sound confronting, but Cameron was not delivering a doom-and-gloom message.
As he said throughout the tour, “This is where the fun happens.”
Volatility creates risk, but it also creates opportunity. Businesses that stay close to their numbers, make decisions quickly and remain disciplined can take ground from competitors who are slower to respond.
That creates an important change in emphasis. This may not be the time to focus solely on growing the overall revenue. It may be the time to focus on winning market share.
The businesses that gain ground over the next few years may not be those with the biggest plans. They may simply be those that execute better, understand their customers and make clearer decisions.
Productivity: the number New Zealand cannot ignore
Perhaps the most damning statistic discussed during the tour was New Zealand’s productivity performance.
Depending on the precise period and measure used, New Zealand’s labour productivity has increased by only around 0.3% to 0.4% a year over the past decade.
What does productivity actually mean?
At its simplest, productivity measures how efficiently we turn inputs into outputs. Labour productivity is generally measured as the amount of real economic value produced for each hour worked.
It is not about asking people to work longer hours or run faster. It is about producing more value from the same amount of time—or producing the same value with fewer resources. Better technology, improved systems, stronger management, investment in equipment, staff capability and removing unnecessary barriers can all increase productivity.
To put New Zealand’s performance into perspective, labour productivity in the United States nonfarm business sector was 2.9% higher in the March 2026 quarter than it had been a year earlier.
That is not a perfectly like-for-like comparison because the two countries define and measure their productive sectors slightly differently. However, it still provides a sobering sense of scale.
On Cameron’s 0.3% benchmark, the United States achieved close to a decade of New Zealand’s recent productivity growth in a single year.
That is a horrible statistic for New Zealand.
Productivity is ultimately what allows businesses to pay higher wages, remain internationally competitive, invest in better technology and generate the tax revenue needed to support healthcare, education, infrastructure and other public services.
Without productivity growth, increasing incomes becomes much harder. We either work more hours, add more people, take on more debt or accept lower living standards relative to the rest of the world.
Farmers are showing what is possible
When we scratch beneath the national average, the picture becomes even more revealing.
Using Stats NZ’s annual industry figures, labour productivity in agriculture increased by an average of approximately 2% a year between 2017 and 2025.
The annual results naturally move around because farming is affected by weather, commodity prices, production cycles and other conditions. But the underlying trend is clear: farmers have continued finding ways to produce more value from their land, labour, equipment and technology.
Our farmers are doing an excellent job. They are investing in genetics, technology, irrigation, systems, data and better on-farm practices. They are adapting to changing regulations, environmental expectations, labour shortages and volatile international markets.
It also brings us back to Cameron’s challenge around the zero line: Can we get out of productive businesses’ way and let them do what they are good at?
If agriculture is achieving productivity gains of around 2% a year while New Zealand’s overall measured-sector average is only around 0.3% to 0.4%, the maths is uncomfortable.
It means significant parts of the economy must be achieving almost no productivity improvement, or going backwards, to drag the national average down so substantially.
This is not about criticising individual workers, New Zealanders work hard, it’s about the systems around them.
Where we invest, the quality of our infrastructure, the technology businesses can access, management capability, regulation, access to capital and whether our institutions make it easier or harder to get things done.
We should be studying the industries that are successfully lifting productivity and asking what can be learned from them.
Unless New Zealand finds a way to produce more value from every hour worked and every dollar invested (Return on Capital), our wages, public services and standard of living will continue falling behind the countries that we compare ourselves.
Banking: taking real risk for real return
One of Cameron’s strongest challenges was that New Zealand needs to become more comfortable with taking real risk for real return.
“We have more road-cones than sheep! We don’t know how to manage risk”
That raises a difficult question about our banking system.
Banks frequently talk about backing business but many business owners find that lending still needs to be supported by residential property. The bank may be lending to the company, but the ultimate security is often the owner’s home and personal guarantee.
Reserve Bank data illustrates the wider structural shift. In June 2026, housing lending stood at approximately $400.5 billion, compared with $143.2 billion of business lending and $64.5 billion of agricultural lending. Excluding personal lending, that means housing represents roughly 66% of lending across those three categories, while business and agriculture account for around 34%.
Using the same Reserve Bank series, the comparable split in mid-1998 was approximately 53% housing and 47% business and agriculture. Nearly ½ and ½ rather than 2/3rds 1/3rd, the balance has shifted heavily towards housing.
This matters because New Zealand will not lift productivity simply by selling increasingly expensive houses to one another.
We need capital flowing into businesses, farms, technology, equipment, exports and people. Those investments carry more genuine commercial risk than lending against an established house, but they are also where sustainable productivity and higher incomes come from.
That does not mean banks should lend recklessly. It means businesses, advisers, banks and policymakers need to find better ways to assess productive opportunities and share risk.
Cameron’s business Chaperon works directly in this space, helping businesses improve their bankability, understand their lending structures and negotiate more effectively with financiers.
Education: today’s classrooms are tomorrow’s economy
Another powerful theme was education.
Cameron described school attendance as potentially one of our most important future economic indicators.
That makes sense. Tomorrow’s workforce participation, productivity, innovation and social outcomes are being influenced by what is happening in classrooms today.
Attendance improved nationally in early 2026, but the regional differences remain significant. Otago recorded the country’s highest regional attendance rate in Term 1 at 73%, with Canterbury and Southland close behind at 72%.
That is encouraging for the South, but it should not create complacency. New Zealand’s overall attendance and educational performance still need considerable improvement.
Cameron said when he talks about Educational stats in Gisborne and Northland, “it’s about as cheerful as a coroner’s retirement speech”.
Education is not simply a government or school issue. It affects employers, families and communities. Businesses will eventually feel the consequences through workforce readiness, basic skills, resilience and the availability of capable people.
An economic strategy that ignores education is not really an economic strategy. We spent twice as much on untargetted winter energy subsidies than we did on helping the children in need achieve beter educational outcomes.
Politics: what a difference a few months can make
When we began the tour, Cameron’s assessment was that the current National-led coalition appeared more likely than not to return to government.
The political mood now looks considerably less certain.
The July Ipsos New Zealand Issues Monitor surveyed 1,002 adults and found Labour was perceived as the party most capable of managing all five of New Zealanders’ leading concerns: cost of living, healthcare, the economy, housing and unemployment.
Labour also overtook National on economic management, with 34% selecting Labour and 30% selecting National. The Government received an average performance rating of 4.1 out of 10, with 24% giving it a positive score of seven or higher.
It is important to be clear: the Ipsos Issues Monitor is not a party-vote poll, and it does not tell us who will form the next government.
However, it does reveal a meaningful change in public perception. Labour is now being credited with greater capability across the issues that New Zealanders say matter most.
That is especially interesting from our perspective. Many people within our immediate business network would traditionally lean towards National or ACT. It would not be unusual for perhaps 80% of a room of small business owners to sit somewhere around the centre-right.
Are those people genuinely moving left?
We would be interested to hear what our clients think.
One July Taxpayers’ Union-Curia party-vote poll had Labour narrowly ahead of National, at 31.5% to 30.5%, but still projected the current National–ACT–New Zealand First coalition to retain a narrow parliamentary majority.
The same poll had approximately 38% of decided voters supporting parties other than Labour or National.
It would be too simplistic to describe all of that support as extreme. What it does show is a more fragmented electorate.
Our suspicion is that some disappointed National voters may not necessarily cross directly to Labour. They may move sideways towards ACT, New Zealand First or the Opportunity Party—or simply become less engaged.
That creates a real challenge for National. Negative coverage surrounding Christopher Luxon’s recent comments with small business owners may weaken its traditional support among that audience, but losing those voters does not automatically strengthen the centre-left bloc.
This election may therefore be decided as much by the movement between parties on the same side of the political spectrum as by voters crossing from right to left.
Why Sidekick hosts these events
For Sidekick, these events are about much more than hearing an economic presentation.
Our mission is to help our clients be more successful, and bringing people together is an important part of that.
We are a people-driven organisation. We want our clients to understand what is happening beyond their own businesses, meet other people facing similar challenges and leave with ideas they can use.
Over the coming year, we will continue sharing Cameron’s thinking with our clients and communities. We are also looking forward to taking to the road again next year with another Roadshow.
Keep an eye out for upcoming Sidekick events, and please reach out to your Sidekick adviser to discuss what these economic, financial and regional changes could mean for your business.
Thank you, Cameron
A huge thank you to Cameron for his energy, openness, humour and outstanding effort throughout the tour.
Cameron has a rare ability to turn complicated economic information into practical, straight-talking insights that people can understand and act on.
You can follow his economic analysis through Bagrie Economics, which provides independent economic research, presentations and strategic advice.
Cameron is also involved with Chaperon, supporting businesses to become more bankable and navigate their financing relationships, and Equity Release NZ, which provides independent information about equity-release and reverse-mortgage options.
We are in a fascinating, and occasionally uncomfortable, economic period.
The old playbook may no longer work. But for disciplined, informed and adaptable businesses, there is still plenty of opportunity ahead.
One final note that might make you smile, Cameron thinks that Aussies are in for a shocking couple of years and New Zealand will gain a lot from that! That will teach them for that under-arm bowl!
Thank you for your interest in this article if you got this far!
Ric Thorpe
CEO
Sidekick Rural insights 2026
Do you know your numbers?
Select the report that fits your situation best.
Farming is easier with a Sidekick
Our clients value local advisors backed by a nationwide network, real-time insights, and advice that goes beyond tax. We help you stay in control, plan ahead, and make confident decisions… all year round.
Growth starts with one call book yours today.
End of financial year resources for farmers
Year End is easier with a Sidekick
Select checklist that fits your situation best.
For farmers:
-
How to do a Year-End in XERO (Sidekick Guide)
For farmers with rental properties:
Farming is easier with a Sidekick
Our clients value local advisors backed by a nationwide network, real-time insights, and advice that goes beyond tax. We help you stay in control, plan ahead, and make confident decisions… at EOFY and all year round.
If you’re unsure where to start, or want help from a Sidekick Rural advisor, book a call today.
Get EOFY sorted with our end of financial year resources
Year End is easier with a Sidekick
Choose the checklist that fits your situation best.
For businesses:
-
EOFY checklist (Sidekick Clients)
-
EOFY checklist (DIY your accounts with accounting software)
-
EOFY checklist (DIY your accounts using spreadsheets, or paper records)
-
How to do a Year-End in XERO (Guide)
For property owners:
Why choose Sidekick?
As the world’s first Xero Platinum Partner, we’ve been leading cloud accounting in New Zealand for years with real-time data, and better conversations.
Our clients value local advisors backed by a nationwide network, real-time insights, and advice that goes beyond tax. We help you stay in control, plan ahead, and make confident decisions… at EOFY and all year round.
If you’re unsure where to start, or want help from a Sidekick advisor, head to our locations tab, and book a call.
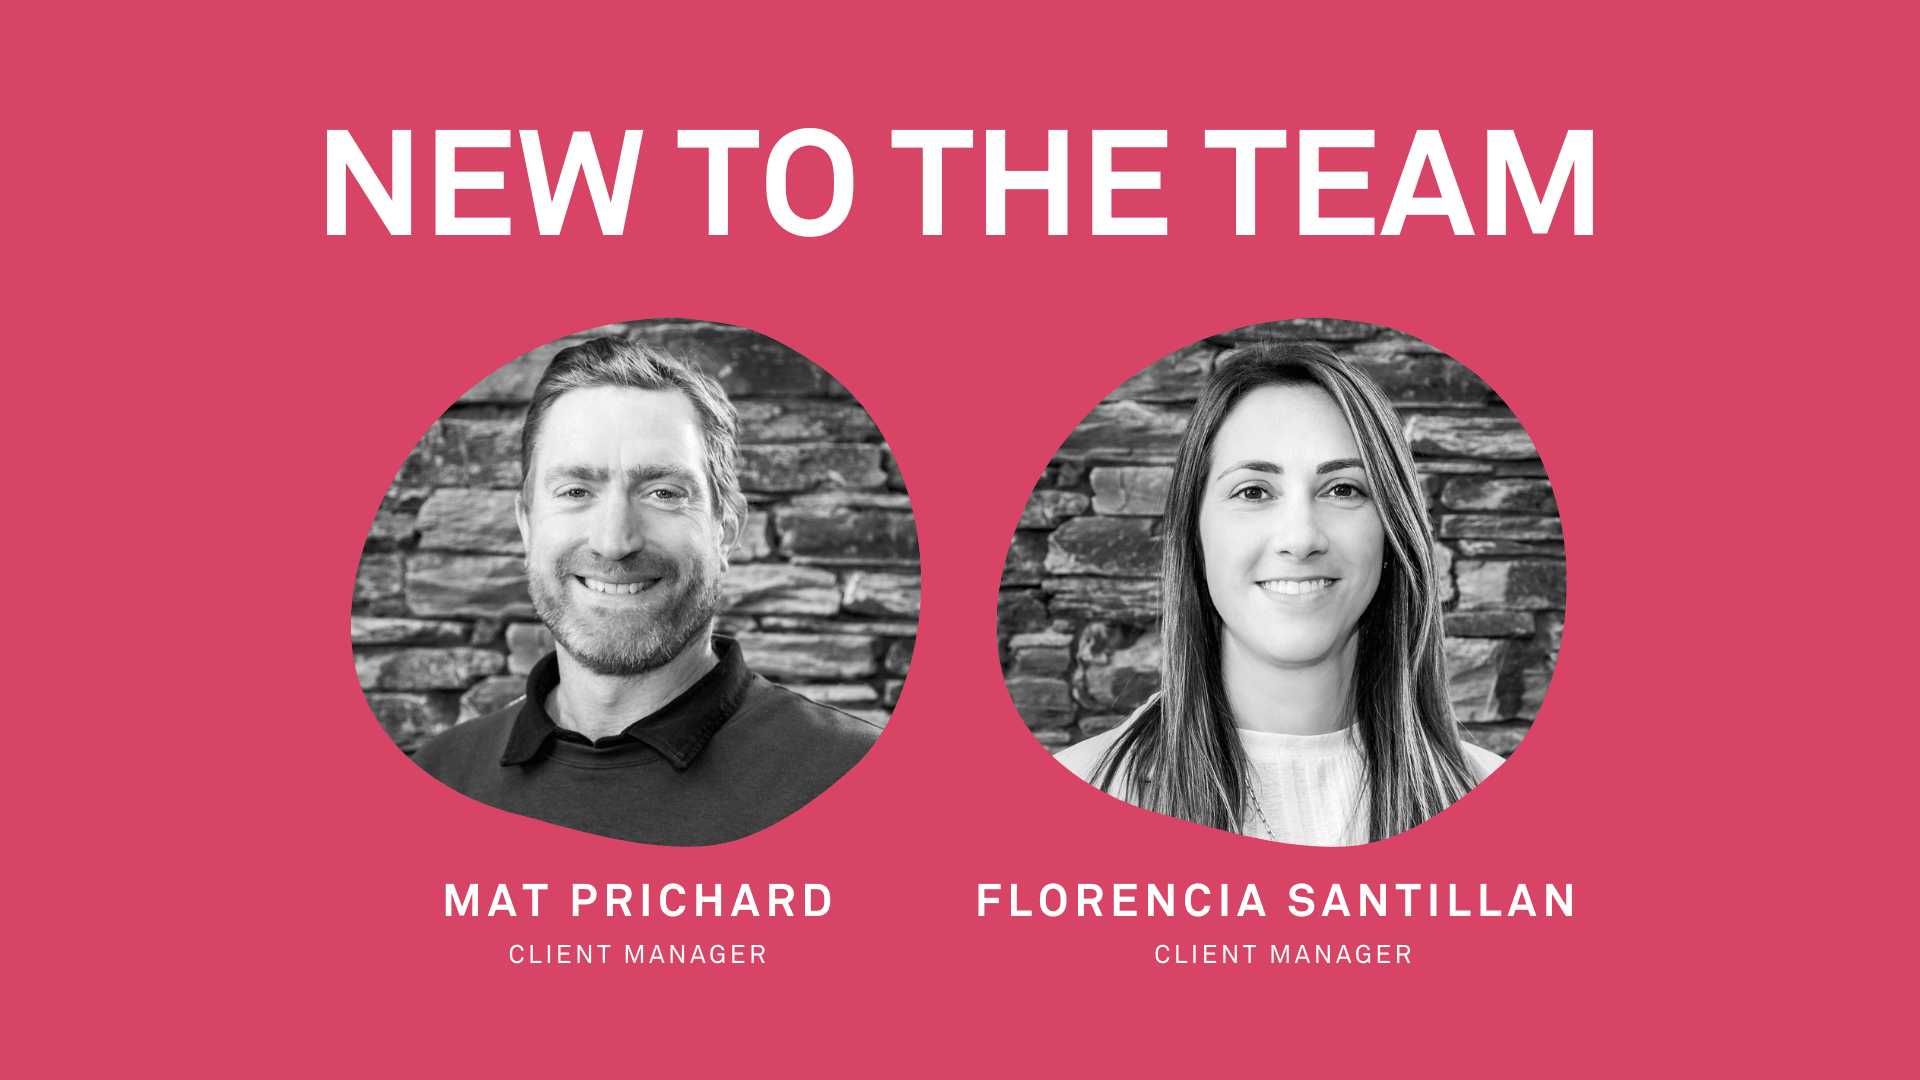
Meet Sidekick Wanaka’s newest members
We are thrilled to welcome two fantastic new members to the Sidekick Wanaka team: Mat Prichard and Florencia Santillan!
Mat Prichard, our new Client Manager, is a familiar face around Wanaka. Many of you might recognise him from his years at Snow Sports NZ or his accounting roles, or perhaps you’ve seen him on the disc golf course. As a qualified Chartered Accountant, Mat brings a wealth of experience and a meticulous approach to managing client relationships and ensuring your financial needs are met with precision and care. We’re excited to have Mat on board and know he’ll be a great asset to our team.
Florencia Santillan also joins us as a new Client Manager with a diverse accounting background. Originally from Argentina with a degree in Public Accounting, Florencia has worked across various industries from Queenstown Resort College to Volvo Car Corp and even in construction in Spain. Her adventurous spirit has also led her to roles in hospitality during her working holiday in New Zealand. Outside the office, Florencia loves snowboarding, paddleboarding, running, and capturing her adventures through photography.
We invite you to book an appointment or pop in to say hello. Discover how our growing team at Sidekick Wanaka can support your financial goals with expertise and a friendly touch!
Improve your work-life balance
Most of us aim for work-life balance, but it can be a tricky thing to do when everything gets busy. Here are a few tips that can assist at any time of year:
- Take holidays – Holidays are great for allowing you to reset your thinking and refresh your mind. Encourage your staff to do the same, this is great for team moral!
- Stay healthy – This is sometimes easier said than done, but it makes a huge difference to how you feel both at work and in your personal life. Keeping healthy will help your mind cope with the stresses and pressures of running a business.
- Learn to delegate – Many hands make light work! Your business will run smoothly and efficiently if you delegate to the right people and let them get on with it.
- Get regular medical check-ups – It can be difficult to see the signs of being overworked when you’re too busy concentrating on all the things you need to get done. Regular check-ups will keep your mind and body in check.
- Switch off – At the end of the day and in the weekends, learn how to switch off properly. This can be hard when we’re all so easily contactable, switching off your emails in the weekends is a good place to start!
Running a small business can be rewarding but also overwhelming – with early starts, long days and often no weekends. If you are feeling the strain, we can help by ensuring you have the systems in place to reduce the paperwork and by assisting you to focus on your goals and priorities.
Please get in contact if you’d like to chat further.
The art of networking: techniques for becoming a great networker
Leading a business can be hard work. But the good news is that you’re not the only founder, owner-manager or CEO who’s treading this path. Networking with your peers is a great way to make connections with other entrepreneurs, while also looking for new business opportunities.
5 ways to improve your networking skills
Being part of a wide network of entrepreneurs and business leaders is about being part of the business community. It’s about giving to the community, as well as being supported by it – and knowing that you’re surrounded by other entrepreneurs who share very similar goals.
So, networking is a valuable thing to take part in, whether you’re a brand new founder, or a seasoned business owner who’s been around the track a few times. But how do you get GOOD at networking? There’s no simple answer to this, but we’ve highlighted five key things you can do to get more from your networking and to give more back to your community.
To become a better networker:
- Be authentic and relational – if you’re going to make a success of networking, it naturally makes sense to appeal to people. Being genuine and interested in getting to know your peers will help a lot. Be yourself, be friendly and take the time to learn about the people you meet. Ask questions about their work, their interests, their goals and what generally makes them tick. This isn’t just about ‘doing business’, remember; it’s about getting to know people as people, and being part of this community.
- Be a good listener and ask thoughtful questions – in networking, listening is just as important as talking. When you’re talking to someone, listen intently, look people in the eye and pay real attention. Resist the temptation to interrupt or start thinking about what you’re going to say next. Instead, focus on understanding their perspective and asking thoughtful questions. Ultimately, you want to make it clear that you’re interested in what this person has to say, and that you’ve found some common ground together.
- Be helpful and offer your expertise – one of the best ways to build relationships is to be an asset to your industry community. Look for ways to use your experience and skills, and offer ideas, advice and help (if people are looking for assistance). This could mean sharing your industry knowledge, providing resources, or making introductions to other people in your network. When you help others, you help the community, underline that you’re a valuable resource and that you’re interested in building relationships.
- Be an asset to your niche/sector/industry – share new ideas, drive innovation and be a voice that stands out in the network. If you want to make an impact, it’s important to stand out from the crowd. A good approach is to be someone who’s known for their expertise, creativity and thought leadership. Get involved in industry discussions, and write articles and blog posts about the big issues in your sector. The more you contribute to your niche/sector/industry, the faster your star will rise.
- Follow up after networking events – getting the networking right is one thing, but it’s important to also get your follow-ups right too. Get people’s business cards, phone numbers or emails and get in touch after the event to touch base. A quick email or LinkedIn message could well be the start of a blossoming new business relationship or friendship. It’s also a good idea to connect on social media and to comment, share and repost your new contact’s posts.
What are the best places for networking?
- Industry-specific events and conferences – industry events are great places to rub shoulders with other professionals in your field. You can get involved in discussions, learn about the latest trends and developments and even present your own sessions.
- Social media platforms – you’re spoilt for choice when it comes to social media sites to help your industry networking. LinkedIn, X(Twitter), Facebook, Threads and BlueSky all help you connect with the people you’ve met through your networking, and build on those relationships to share your insights and ideas more widely.
- Local meetups and workshops – most cities and towns will have regular business meetups and workshops that you can dip into. Business breakfast events and evening get-togethers are a great way to meet local business owners and to find out what’s going on in your local community.
If you’re looking to raise your profile and improve your networking, we’d love to lend a helping hand. We’re connected to hundreds of different business owners and leaders – and we’re more than happy to introduce you.
Our advice is to put yourself out there in your industry community, track down your local business peers and get busy with your content marketing and social media posts.
Are you hiring the best talent for your business culture?
Your people are a vital asset, so when you hire a new starter it’s critical that this new employee fits perfectly into your operations, your culture and your values as a company.
But how do you know if a potential hire is a ‘good fit’? Will they drive your business to bigger and better success, or could this new employee become a potential spanner in the works?
Be transparent about your company values
Your company values are central to your mission as a business. So making sure those values are clearly outlined and shared is essential for hiring the right talent. By clearly defining and sharing these fundamental values, you’ll attract candidates who share your ethics, values and core motivations – making them a great potential fit for your company culture.
To do this:
- Identify your core values and what’s important to you as a business and an owner.
- Communicate your core values to your employees and all new starters
- Live your values. Reflect them in the way you do business and how you treat people
- Communicate your values, mission and culture in your job advert
When you’re hiring, this process isn’t just about you choosing an employee – it’s also about a worker choosing your company and understanding what you stand for. Make sure your job advert gives the best possible indication of what the job entails, but also what you’re like as a workplace. This is a great way to appeal to like-minded people with the best skills.
When advertising and interviewing:
- Describe your mission and ask candidates if they are on board with these goals
- Talk about your culture and ask candidates why this might appeal to them
- Paint the most honest and appealing picture of your workplace
- Ask interview questions that reveal the real candidate
You obviously want to know that a prospective hire has the right mix of experience, knowledge and professional skills. That’s a given. But it’s also sensible to ask questions that reveal more about their underlying values, morality, work ethic and interpersonal skills. This will help you to assess whether the candidate is a good fit for your company culture.
Here are some examples of interview questions that dig a little deeper:
- What do you look for in an ideal employer? And how important are their core values?
- Tell us about a time you faced conflict in the workplace, and how you resolved it
- Our culture is front and centre. How do you see yourself fitting into our culture?
- How do you see your career evolving as a valued team member in our business?
- Ask your team for feedback on candidates
You may think a candidate is the bee’s knees, but what do the rest of your team think? Gauging the opinions of your management team and other team members is vitally important. These people will be working directly with this new hire, so they have to get a good vibe from them.
To encourage objective feedback, give your team members a chance to meet the candidate and take their feedback into account when making a hiring decision.
Monitor your new hire and have regular, ongoing performance reviews
Once you’ve made a hiring decision and have a new employee on the team, it’s vital to have regular and ongoing informal catch-ups and more formalised performance reviews. This helps you to measure how your new employee is settling in. It’s also an opportunity to gauge whether there are areas where they may need support from you and the wider team.
Don’t hold back. Be as open and transparent as possible:
- Ask them how they’re feeling about their role, workload and their performance so far
- Check their progress against set targets and objectives for their first three months.
- Find out if they need help, support, further information or more onboarding support.
- Check if they feel they are fitting into the team, and if they are feeling happy
- Look out for potential issues that may be causing conflict in the team.
Having the very best talent in your team is central to achieving your goals for the business. So, making sure you hire the right people is actually a business-critical decision to make.
The ABCs of bookkeeping
In today’s digital times, you’re probably used to having unrivalled access to your financial numbers, key performance indicators (KPIs) and cashflow metrics. Without good bookkeeping, the speed and quality of your reporting can quickly fall down.
So, why is fast and accurate bookkeeping so important? And what are the main bookkeeping tasks that your business should be getting right?
The financial importance of good bookkeeping
Bookkeeping is a fundamental part of your financial process as a business. Without it, your accounting software has no financial data to work with, your leaders don’t have the most current numbers, and your accountant can’t see the current financial health of the business.
Inputting your financial transaction into some form of record-keeping system is also a mandatory commitment if you’re a registered business and paying goods and services or value-added tax. Bookkeeping is what provides you with a historic breadcrumb trail of your finances – allowing you to track your cashflow, revenues and profits over a given period.
How to maximise your bookkeeping
So, bookkeeping is a vital part of your financial management. And the key to having your transactions recorded, available for reporting and accessible whenever you need them.
But how should the bookkeeping process work, in an ideal world? Let’s walk through the core bookkeeping steps and how you can get the most from this financial admin task.
To keep on top of your bookkeeping:
- Scan all financial paperwork – the initial part of the bookkeeping process is to scan and record all receipts, invoices and remittances. This gives you a digital copy of the paperwork that relates to your income and expenses – important when you get around to filing tax returns and expense claims etc.
- Record all transactions immediately – getting your transaction recorded and in the books ASAP is vital. This includes recording both your income and expenses, as soon as they occur, and matching them with the scanned paperwork. This not only helps you stay organised but also means your financial data is always up-to-date and can provide real-time reporting and numbers. This can be a huge help when running the business.
- Categorise transactions accurately – when recording transactions, make sure you’re accurate and categorise each item correctly. Not only does this remove the potential for errors and miss-keying in your books, it also helps you track your spending and income more accurately, so your reports are an honest reflection of your financial health.
- Reconcile your accounts regularly – reconciliation is the process of matching your transactions (both income and expenses) against your bank statement and other financial statements. It’s a key part of your bookkeeping and should be done regularly, to ensure that your balances are correct and that your records are totally up to date.
- Use a cloud-based accounting system – bookkeeping doesn’t involve books (ledgers, in accounting-speak) anymore. In the digital world, you can use cloud-based accounting software, like Xero, to record your transactions and access your financial data in the cloud from anywhere, at any time. This makes it easier to keep on top of your numbers when out of the office (and Xero will even automate the reconciliation process too).
- Outsource your bookkeeping to a professional – yes, you can do your own bookkeeping. But there’s a LOT of value to delegating all the hard work to a professional bookkeeper. If you don’t have the time or expertise to manage your bookkeeping yourself, outsourcing is a smart move. A bookkeeper will make sure your books are always accurate and under control. Plus, they can produce cashflow statements, revenue forecasts and other reports to help your business decision-making.
Talk to us about outsourcing your bookkeeping
With today’s cloud accounting software, bookkeeping is a far less tedious task than it used to be. But it’s still a regular, time-consuming job that can take you away from running the business.
If you’re thinking about outsourcing your bookkeeping, and freeing up that admin time, we’d love to talk to you. Our outsourced bookkeeping service will take on your bookkeeping tasks, to streamline the whole process. We’ll also introduce you to automated data-entry tools like Hubdoc, that make snapping receipts and scanning invoices a breeze.
Let us do the books, so you can get back to talking to customers and winning work.
Get in touch to discuss our outsourced bookkeeping.
Tips for dealing with economic uncertainty in your business
With political changes and an economic slowdown to contend with, we’re in pretty unpredictable waters. Here are some tips on managing your team in times of uncertainty:
Support staff wellbeing
Talk to staff about wellbeing regularly and openly. Let your team know it’s okay to feel stress or anxiety.
Regularly remind your people where to find support, whether it’s through free counselling or mental health resources, or through company health plans.
Put wellbeing practices in place
Ask your team what could help their wellbeing and balance. Consider team activities, on-the-job skill sharing and learning, and charity events.
Be clear about cost-cutting
Change on the cards? Communicate openly and frequently, using information that is easy to understand, relevant, and factual. Don’t offer false hope or reassurances.
Let people know if there is nothing new to communicate or if you are still working out your plans. Consulting effectively with staff can reduce the stress of uncertainty as you look to make changes in your business.
Client Spotlight: 2B Connected

Client Spotlight: 2B Connected
2B Connected is an outsourced call centre provider who specialise in helping businesses generate more leads for their business utilising their tele-marketing and digital teams. They can also help handle inbound calls from your existing and prospective customers.
Grant & Jemma Walker run the family owned operation out of their call centre in Riccarton, and help businesses of every size, across just about every industry generate more leads for their business everyday.

Their big point of difference is guaranteed results for clients – something which no other marketing company offers, but they believe that standing behind their work, having an outstanding team to back it up and having some shared risk with clients is critical.
Their services include:
- Lead Generation & telemarketing for B2B and B2C
- Customer Service & Support
- Outbound Sales
- Digital Lead Generation
- LinkedIn Lead Generation
- Overflow calling support
- Market Research
- Virtual Receptionist & Data Entry
So if you need help generating more opportunities for your business, help answering calls from your customers or just want to pop in for a coffee and see how a modern call centre operates, then get in touch.
Client Spotlight: Hail
Hail is a fresh and exciting marketing platform that is your one-stop-shop for creating and sharing amazing digital communications.
With minimal setup required you’ll slash your print budget, save the planet and be sharing beautiful, engaging stories with your community straight away. Spread the load by getting the whole team involved and you’ll all reap the rewards of increased community feedback and engagement.
Hail is the software we’ve used to send our Newsletters out in this fresh and exciting format. They’re based locally in Christchurch, so if you are interested in using their software for your marketing publications here’s the link to their Website and their Facebook page.
If you have any questions contact stuart@hail.to for more info

Client-Spotlight-Hail
Client Spotlight: CarMoney
 We love seeing a business that does things better and different and Greg’s business, in the incredibly competitive and cut-throat Vehicle Finance space, has a lot of unique challenges that makes breaking into the industry very tough!
Greg has partnered with a great marketing provider, you may have seen him before, his videos have been watched by over 100,000 people locally!
This finance business is growing fast and competing incredibly well against the incumbents but what’s more important – in our book – is that they’re committed to lending to Kiwis on terms that are affordable for their current needs, as well as for the long term. Their team are always happy to answer any questions you have, and furthermore you’ll receive one-to-one service throughout your loan application process.
They are a very valued client of ours, and we thoroughly enjoy working with them since inception. CarMoney has grown to be very successful in the last year, and it has been great supporting Greg throughout this process and to help him explore new business pathways, tax savings and a set a plan to build enduring wealth – it’s this type of engagement that spins our wheels!
Check out the CarMoney Website with it’s interactive features and calculator and Facebook page (if you haven’t already seen the videos there)